
Mukesh Ambani: Reading Business Beyond Net Worth
Use Reliance’s official profile to understand Mukesh Ambani’s corporate role, then distinguish revenue, company value and personal wealth estimates.
Mukesh Ambani is identified as chairman and managing director in Reliance Industries' official annual reporting. To understand his business role, begin with the company, its accounts and its governance structure. A personal wealth headline answers a different question from a financial statement, and neither should be used as a substitute for the other.
This reading guide uses Reliance as a practical case for business literacy. It explains how to distinguish revenue, profit, company value and ownership, then connect those concepts to disclosures. The worked figures below are invented classroom examples, not Reliance results, share-price forecasts or estimates of Ambani's assets. They help readers interpret real documents without manufacturing current financial claims.
Why is Mukesh Ambani's corporate role different from ownership?
A corporate role describes responsibilities inside a particular legal entity. Ownership describes an economic interest in shares or other assets. Someone can hold an executive office and own shares, but the two facts require different evidence. Read the board report for responsibilities and the shareholding disclosure for ownership rather than assuming that one establishes the other.
Chairman and managing director are governance titles. Their precise responsibilities should be read in the company's documents, alongside the board of directors and management structure. A familiar surname cannot establish authority over every subsidiary. Always identify the exact company, effective date and office before describing who made a decision or who is accountable for it.
Consider a hypothetical group containing a manufacturer and a retailer. The parent company's leader may oversee overall strategy while a subsidiary has its own directors and operating management. A decision announced by the retailer cannot automatically be attributed personally to the group chairman. Company announcements, board approvals and delegated responsibilities help separate those layers.
For a short business profile, write three factual sentences: the entity's name, the documented position and the source period. Then explain the analytical question you want to investigate. This gives the reader a usable starting point without expanding a leadership title into unsupported claims about personal control, daily involvement or ownership of every asset associated with the group.
Why are revenue, profit and cash flow different?
Revenue measures recognised sales or operating income under the applicable accounting definitions. Profit reflects income after specified expenses. Cash flow records movements of cash under defined categories. A business can report growing revenue while experiencing pressure on margins or cash, so these figures should be read together and with their accounting notes.
Use a hypothetical company with sales of 1,000 units of currency and operating costs of 850. Its simplified operating profit is 150 before any additional items excluded from that example. If customers have not yet paid for some sales, cash received can be lower than reported revenue. The timing difference helps explain why profit and bank balances are not interchangeable.
The income statement, balance sheet and cash flow statement describe related views of the business. The first covers performance over a period, the second a position at a date and the third cash movements during a period. Read the labels before calculating ratios. An annual total cannot be compared directly with a single-quarter figure and called growth.
Watch for measures such as EBITDA and net profit. A company may define adjusted measures differently from another business, so examine the reconciliation and notes. A large EBITDA figure does not mean all of that amount is available for shareholders. Interest, tax, investment needs and other commitments can matter when interpreting what the operating figure actually tells you.
How does market capitalisation differ from personal net worth?
Market capitalisation is the market value of a listed company's equity, commonly calculated from share price and shares outstanding. Personal net worth estimates concern an individual's assets minus liabilities under an estimator's assumptions. Neither is the same as salary, company revenue or cash personally available to spend at the moment of a headline.
Suppose a fictional listed company has 100 million shares trading at 20 currency units. Its market capitalisation is two billion. An individual owning ten million shares has a quoted stake worth 200 million at that price, before considering restrictions, debt, taxes or other assets. The example explains the calculation; it does not value a real person's holdings.
A change in share price changes the quoted value of an ownership stake. It does not necessarily mean that the holder received or paid the same amount of cash that day. Sale proceeds require a transaction. Liquidity, ownership structures and the ability to sell a large holding also complicate any attempt to translate paper value into spendable money.
For billionaire rankings, record the estimate date, currency and methodology. Two estimates may differ because of timing or treatment of unlisted assets. Avoid selecting whichever number looks most dramatic. A responsible summary explains the basis of the estimate and keeps it separate from audited company accounts. This article intentionally avoids a current wealth ranking or a fixed net worth figure.
What should readers learn from consolidated and standalone accounts?
Standalone accounts describe the reporting company under the relevant framework. Consolidated accounts combine a parent and qualifying entities according to accounting rules. They answer different questions. Before comparing figures, identify which set you are using and whether the previous year's comparator uses the same scope and reporting basis.
Imagine a parent company selling materials to its subsidiary. Looking at each entity separately reveals their individual transactions. Combining them requires adjustments so that internal business does not look like an external sale twice. That simplified example explains why adding every subsidiary's revenue to the parent's headline total can produce a misleading group figure.
The notes explain the consolidation boundary and changes during the reporting period. Acquisitions, disposals or reorganisations can affect comparability. If revenue rises after a business is acquired, distinguish the expanded reporting scope from growth in the existing operations. Both can matter, but they tell different stories about the source of the change.
Keep a small document header in your notebook: financial year, currency, units, reporting scope and audit status. If a table states amounts in crore, do not silently treat them as individual rupees. If one report uses millions and another uses billions, convert consistently before comparison. Many apparent contradictions disappear once readers restore the missing labels.
How can a diversified group's business segments be compared?
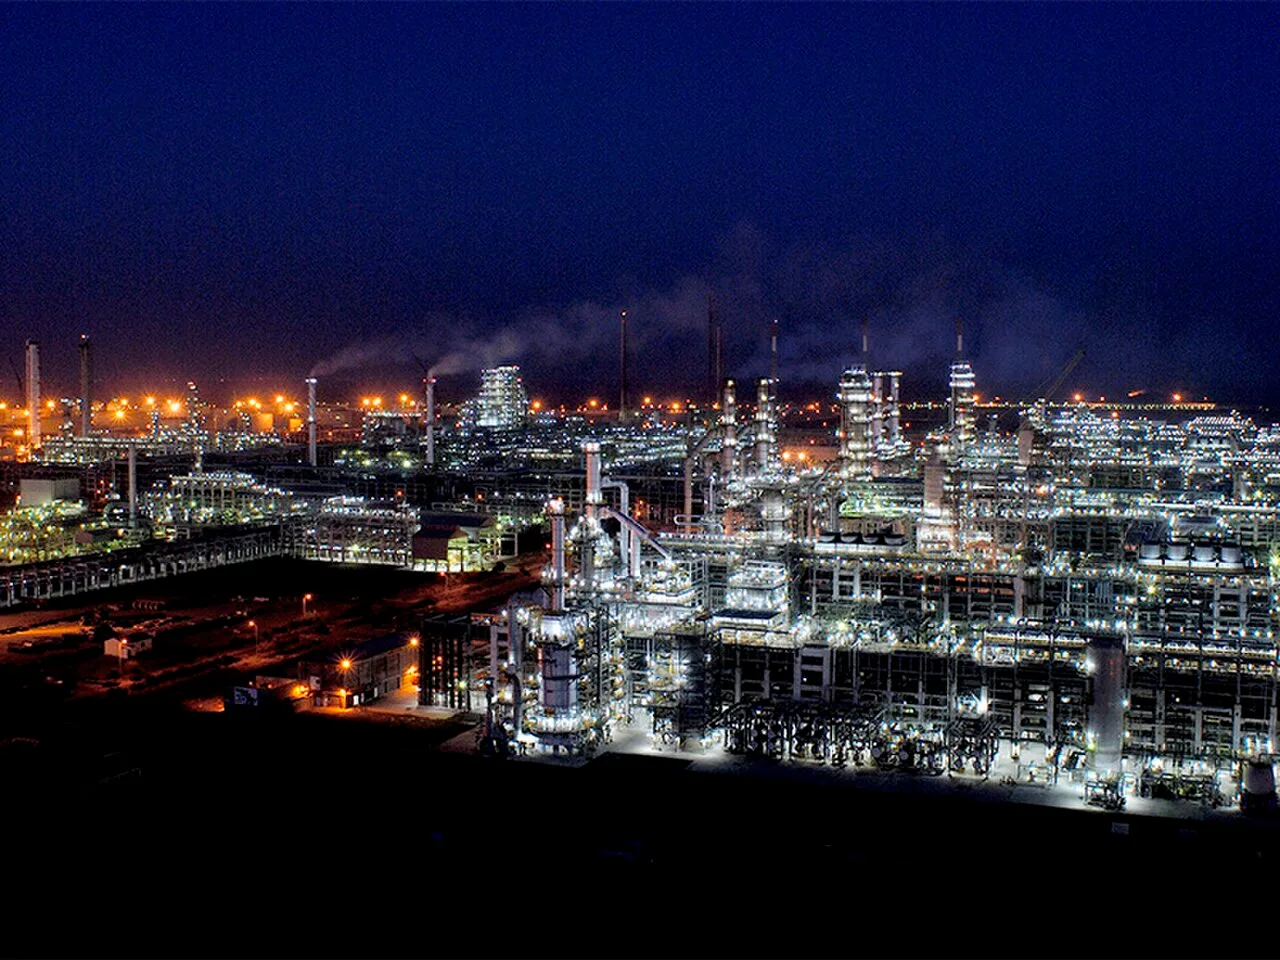
Jamnagar refinery in a 2006 photograph, illustrating an industrial business segment rather than personal wealth.
Segment reporting divides a group into disclosed activities so readers can examine how different operations contribute. Compare segment revenue, operating result and capital employed only after reading their definitions. Strong performance in one activity does not establish that every business within the group has the same margins, investment needs or risks.
For a classroom exercise, imagine a retail segment with revenue of 500 and operating profit of 25, alongside a services segment with revenue of 200 and operating profit of 30. Their simplified operating margins are five percent and fifteen percent. The bigger revenue contributor is not automatically the bigger profit contributor, and neither ratio alone establishes investment quality.
Consider business models alongside numbers. A shop network may require inventory, premises and distribution. A digital service may involve network investment, customer acquisition and ongoing technology spending. Those are analytical questions to examine in disclosures, not grounds for assuming that one model is always better. Ask which costs and assets support the reported result.
Read inter-segment transactions, unallocated items and reconciliation to group totals where provided. A segment chart may simplify a more complicated accounting structure. The annual report's segment note is more useful for comparison than a promotional graphic alone. Keep the scope consistent when comparing a segment across years or with a competitor whose categories may be organised differently.
What does corporate governance evidence actually show?
Corporate governance materials describe structures for oversight, decision-making and reporting. Relevant evidence includes board composition, committee responsibilities, attendance disclosures, related party transactions and the auditor's report. These documents provide specific questions to investigate; the existence of a policy does not by itself prove that every outcome meets that policy's stated ambitions.
Distinguish executive directors, non-executive directors and independent directors using the report's definitions and applicable disclosures. Committee names alone reveal little about a particular decision. Check the committee's remit and the relevant reporting period. A person serving on one committee is not automatically responsible for every operational action carried out across the group.
Related party disclosures deserve careful reading because they identify transactions involving specified relationships. Their presence is not proof of wrongdoing. Equally, a familiar family or corporate relationship should not be ignored when the report explains how transactions are reviewed. A balanced analysis describes the relationship, transaction and oversight process without turning association into an allegation.
Read the audit opinion and any qualifications in their exact context. Audited financial statements do not guarantee future profits or certify every sentence in a chairman's message. Management commentary, audited accounts and sustainability narratives can have different assurance boundaries. Your summary should preserve those distinctions instead of attaching one broad seal of certainty to an entire report.
How can students identify unsupported business headlines?
Test a headline by asking what quantity changed, over which period, in which entity and according to which document. A percentage without its base is incomplete. A statement about company sales cannot automatically support a claim about personal earnings, and a share-price move does not prove a new operating development by itself.
Consider the phrase “business doubles.” It might mean revenue, profit, subscribers, store count or market value. Each requires different evidence. Rewrite it as a precise sentence using the actual measure. If only a customer count doubled, do not describe profits as doubling. If the comparison is quarterly, retain that period instead of presenting it as an annual result.
Currency creates another common trap. A rupee result translated into dollars can move because of both operating performance and the exchange rate used. Do not compare figures converted at different dates without acknowledging the method. A cleaner exercise first compares results in the reporting currency, then explains any conversion separately with its date and assumptions.
Keep claims about strategy distinct from established outcomes. An investment announcement states an intention or commitment under stated conditions. It does not prove that every facility is built, every customer is acquired or every projected return is earned. Follow later disclosures for implementation rather than treating a large announced amount as completed economic activity.
How can you build a useful one-page Reliance reading note?
Choose one question, one reporting period and a small number of comparable measures. A good note explains the business meaning of those measures and identifies what remains unresolved. It should let another reader reproduce your reasoning from the same documents without relying on your confidence, a personality profile or a wealth headline.
Begin with a question such as whether a segment's margin changed. Record its revenue and relevant operating measure for two comparable periods, retaining units. Calculate the ratio transparently and inspect the report for changes in scope. Then write a paragraph explaining which observed changes could account for the result and which explanations the evidence does not establish.
Add a governance question where it affects interpretation. For example, an acquisition may require attention to ownership and consolidation notes. An investment programme may require a comparison of capital expenditure and operating cash generation. These connections turn accounting terms into a business explanation without pretending that a simple ratio captures every risk or managerial decision.
End with a concise limitation tied to the task. If your material covers an earlier financial year, say so. If a figure is management's estimate, label it accordingly. Avoid filling the gap with a confident forecast. The aim is a defensible reading of published information, which is useful whether you are studying commerce, writing an essay or evaluating a news report.
A comparison for the notebook
| Measure | Main question | Common mistake |
|---|---|---|
| Revenue | What income was recognised? | Calling it personal earnings |
| Operating profit | What remained after specified operating costs? | Treating it as cash |
| Cash flow | How did cash move? | Assuming it equals profit |
| Market capitalisation | What is quoted equity worth? | Calling it company sales |
| Net worth estimate | What assets and liabilities are attributed to a person? | Presenting it as audited income |
Use the table when revising a business paragraph. Underline each number and label the measure, entity and period beside it. If one label is missing, find it before making a comparison. This small editing exercise often improves a report more than adding another page of biography because it addresses the exact places where readers can misunderstand financial information.
Work through a growth comparison
Suppose a fictional segment reports revenue of 120 after reporting 100 in the comparable earlier period. The increase is twenty percent, calculated from the change of twenty divided by the earlier base of one hundred. If its operating profit moves from ten to eleven, profit grows more slowly than revenue. That combination invites a question about margins; it does not answer the question by itself.
Read the operating explanation and accounting notes before assigning a cause. Higher costs, a changed product mix or a different reporting boundary are possibilities to investigate, not facts to insert automatically. The corporate-role source guide helps keep ownership and management labels separate during that reading.
A second edit checks economic context. The Pakistan economy guide explains why the measure and period matter, while the inflation guide distinguishes price changes from quantities. Apply those distinctions without assuming that a national indicator directly explains one company's result. The final note should separate the calculation, the disclosed explanation and your unresolved question.
Sources
Image credits: Cover: World Economic Forum, source, CC BY-SA 2.0. Resized and converted to WebP. Article image: Reliance Industries, source, CC BY-SA 4.0. Resized and converted to WebP.
Found an error or an outdated detail? Report a correction with the article URL and original source.