
Anant Ambani: Corporate Roles and Public Claims
Read Anant Ambani’s corporate profile with care, distinguish a board role from ownership, and evaluate public claims using company disclosures.
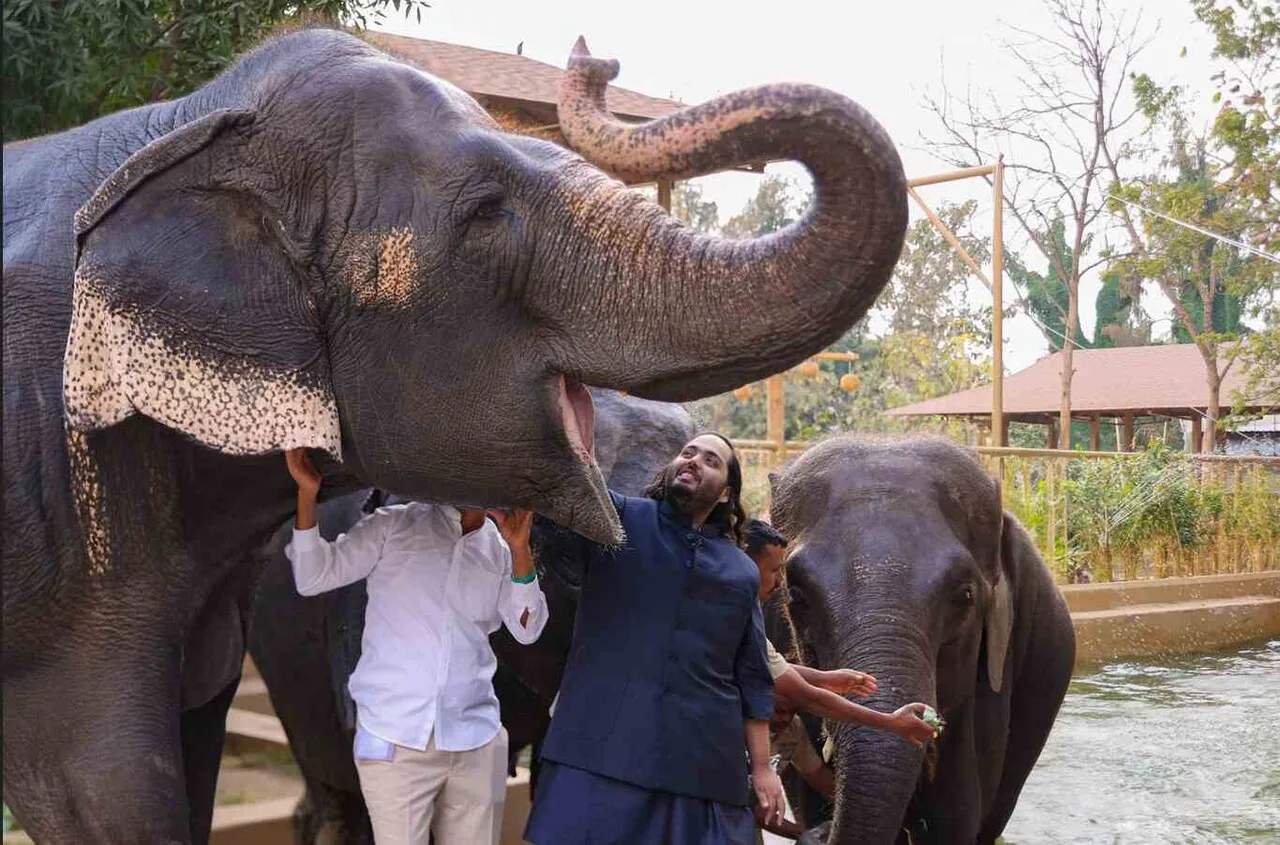
Reliance Industries' official profile lists Anant M. Ambani as an Executive Director. Its 2025-26 annual report records his appointment as a whole-time director, designated Executive Director, effective 1 May 2025. Those are specific corporate-role statements. They should be distinguished from personal wealth estimates, promotional assessments of achievement and claims about the results of individual projects.
For students, the useful question is how to read the public record behind a prominent business name. A profile, annual report, board listing and sustainability statement each provide different evidence. This guide explains how to identify the legal entity, date a role correctly, read basic business figures and assess public-impact claims without assuming that family association or a photograph proves management responsibility.
Which source should you use to establish a corporate role?
Use the company's current board listing and the relevant dated appointment disclosure or annual report. A biography can identify the title the company currently presents, while a filing or report can establish the effective date and terms described at that time. Read both when constructing a role history.
Begin with the full legal entity name. Reliance Industries, a subsidiary and a foundation are not interchangeable organisations. A person can hold roles in more than one entity, but that does not make the titles identical. Copy the entity alongside the role rather than relying on a group name alone.
Then record the date attached to the evidence. Publication date, approval date and effective date can differ. A report published after an appointment may describe a role that began earlier. If you present the publication date as the appointment date, the timeline becomes wrong despite using an official document.
The profile is a primary source for what the organisation says about its director. It is not an independent evaluation of every adjective in the biography. Separate a verifiable title from statements praising influence, vision or impact, which require different kinds of supporting evidence.
For a wider reading exercise, compare this method with the Mukesh Ambani governance guide. The subject is related, but each individual's role still requires its own entity, date and supporting record rather than being inferred from a shared surname.
How are a board role, executive job and ownership different?
Governance, management and ownership describe different relationships with a company. A board role concerns participation in its governing structure; an executive job concerns operational responsibilities; ownership concerns an economic interest. These can overlap in one person, but evidence of one relationship does not automatically establish the others.
A non-executive role and an executive role should therefore not be treated as equivalent labels. Similarly, an independent director has a distinct governance designation that should be copied from the current official record. This article explains the reading distinction rather than offering a legal determination of anyone's duties or independence.
Ownership needs shareholding evidence. A public appearance, family connection or senior title does not specify the number of shares a person owns. Where shares are held through entities or arrangements, the reporting structure needs careful reading before an economic interest is attributed to one individual.
Consider a fictional company whose founder owns shares but no longer manages daily operations. Another person may lead operations without a large personal stake. Both can be influential, but in different ways. A clear business profile identifies the relationship it is discussing instead of reducing every form of influence to ownership.
A useful note-taking rule is one row per relationship. List the individual, organisation, role, date and document. If you cannot fill a field, mark it unresolved rather than borrowing the answer from another company in the group. This creates a reliable map before you begin interpreting influence.
What do board committees tell you about governance?
Board committees show how particular oversight responsibilities are organised, subject to their published terms and membership. An audit committee, a remuneration-related committee and another governance committee can have different tasks. Read the actual remit before assuming that membership means direct responsibility for every operational result.
The company's committee page is a starting source for names and stated responsibilities. Match the period you are analysing with the appropriate record. A current membership list may differ from one printed in an earlier annual report, so a historical claim needs historical evidence.
An audit-related role should not be confused with personally preparing every financial statement. Governance arrangements involve management, oversight and professional reporting functions. Likewise, a committee considering remuneration policy does not necessarily determine every individual payment in the simple way a headline might suggest.
A role-reading worksheet
| Question | Record to examine | Mistake to avoid |
|---|---|---|
| What is the title? | Board profile and appointment disclosure | Inferring from a family name |
| When did it apply? | Dated filing or annual report | Using publication date automatically |
| Which entity? | Full legal name | Merging parent and subsidiary |
| What is the remit? | Committee terms or role disclosure | Assuming control over every activity |
| Who owns shares? | Relevant shareholding record | Equating a title with ownership |
Conflict of interest is another issue to investigate through disclosed processes rather than speculation. Ask what relationships or transactions are reported and what review procedures apply. A question about governance is legitimate; an allegation requires evidence specific enough to support it.
How should you read revenue, profit and cash flow?
Revenue, profit and cash flow answer different questions about a business. Revenue concerns sales or income recognised during a period; profit reflects income after the relevant expenses; cash flow concerns actual cash movement. A large number in one category does not automatically imply an equally large number in the others.
The SEC's introductory financial-statement guide explains these distinctions and the relationship between statements. Use the income statement for a defined period and the balance sheet for a point-in-time view of assets, liabilities and equity. Check the units before comparing figures.
For a fictional example, a business can record one hundred units of revenue and eighty of relevant expenses, leaving twenty before other specified items. That does not mean twenty units of cash arrived during the period. Customer payment timing and other cash movements can produce a different cash result.
Read operating profit and net profit with their labels intact. A report may also discuss capital expenditure, borrowing or dividend payments. Those items belong to different parts of the business story. Do not subtract or add them casually without understanding the accounting measure you are trying to reproduce.
The Pakistan economy indicators guide offers a useful comparison at a different scale: related economic measures should also remain distinct. In both company and national analysis, the first task is defining the number, period and unit before explaining why it rose or fell.
Why must consolidated and standalone figures stay separate?
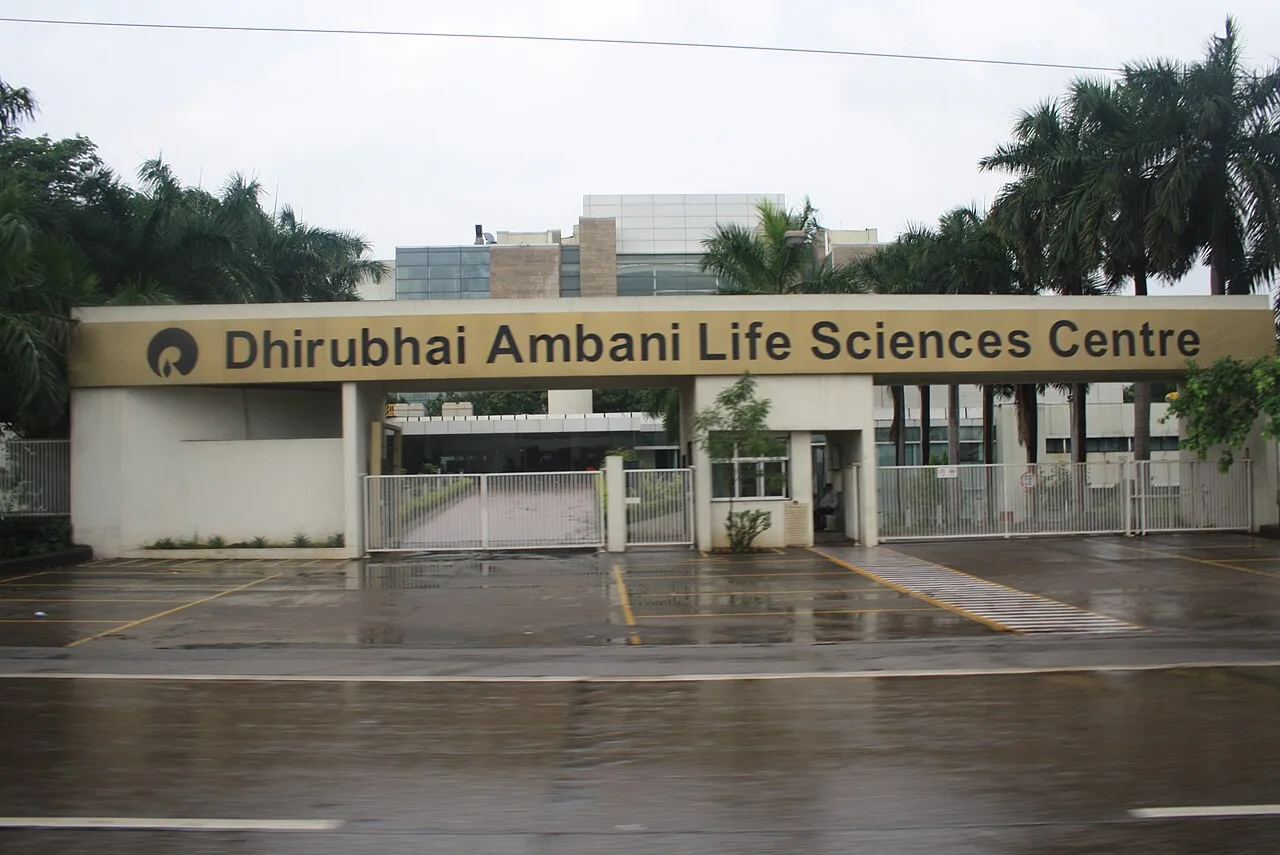
A historical facility entrance illustrates why the exact corporate entity matters; it does not establish an individual's ownership or responsibilities.
Consolidated and standalone statements describe different reporting boundaries. A consolidated view brings together the reporting group under the applicable framework, while a standalone view concerns the reporting company on its own basis. Read the statement heading before comparing numbers or attributing a segment's results to the entire group.
A subsidiary may operate a particular business while the parent has other activities. Adding a subsidiary's revenue to an already consolidated group total can double count the same activity. The relevant report should explain which entities and transactions are included in the reported boundary.
Use a fictional diagram with a parent and two subsidiaries. Give each a separate box, then draw a larger boundary around the group. Before calculating anything, decide whether your question concerns one box or the whole boundary. That simple drawing can prevent a surprisingly large reporting error.
Reporting period also matters. A quarter, half-year and financial year are not interchangeable samples. A comparison between a full year and a single quarter may be valid for a specific exercise, but it should not be presented as an ordinary growth rate without explanation.
Keep currency and scale beside the figure. Rupees, crores and billions can be mixed accidentally when a headline is rewritten for another audience. If you convert a figure, retain the original amount and state the conversion basis. Do not let a formatting change create a false increase in the business's reported size.
Why is net worth different from company value or cash?
Net worth is an estimate of assets minus liabilities, not a bank balance or a company's annual revenue. Market capitalisation concerns the market value of outstanding equity at a particular share price. Neither figure automatically becomes the personal wealth of one director, even when that person is closely associated with the business.
Personal valuation estimates can depend on ownership assumptions, listed-share prices, private assets and debt. Different methods and dates can therefore produce different results. Without a clear methodology and identified interests, repeating a precise personal fortune can create an impression of certainty that the evidence does not support.
A fictional investor owning ten per cent of a listed company does not own the entire company's value. Even the proportional market value of that stake is not necessarily immediately available cash. Selling, restrictions, liabilities and market movements are separate issues that a simple multiplication does not resolve.
The dollar-rate guide explains why currency figures also need a date and defined rate. A wealth estimate converted at one exchange rate cannot be compared casually with another using a different date and method.
For a corporate-role article, ask whether a fortune estimate contributes to the learning question at all. Understanding governance, strategy and reporting often requires no personal wealth number. Avoid introducing an uncertain valuation merely because it attracts attention when the substantive issue is the role and evidence behind a public business claim.
How should sustainability and conservation claims be tested?
Treat a sustainability or conservation claim as a proposition requiring a defined activity, period, metric and outcome. The company profile associates Anant Ambani with Vantara and conservation work, but that corporate description is not itself an independent evaluation of welfare or ecological effectiveness. Assess the supporting records separately.
Start by identifying what is being measured. An activity count, an expenditure total and an outcome measure describe different things. Money spent can establish an input; it does not by itself establish a lasting benefit. Likewise, a photograph can show an event without demonstrating a trend.
A target needs a baseline, deadline and scope. If a statement promises improvement, ask improvement relative to what year, covering which activities and measured how. The IFRS Foundation's sustainability-disclosure material emphasises governance, strategy, risks and metrics, a useful framework for organising those questions without claiming that every public initiative follows the same reporting requirements.
Assurance also needs its scope read carefully. An external review may cover selected indicators rather than every claim in a report. Identify which measures were checked, for what period and under what stated basis. Do not turn a limited assurance statement into blanket validation of every promotional sentence.
For a classroom example, compare a fictional rescue programme's number of admissions with its documented long-term care outcomes. Both can be useful, but they answer different questions. This teaches a constructive form of scepticism: ask for the evidence that would demonstrate the claimed result instead of praising or rejecting it from the organisation's reputation alone.
How can students build a reliable Anant Ambani source brief?
Build a short brief organised by claims rather than celebrity anecdotes. Establish the current title, document the role timeline, separate ownership from management and choose one business or impact question to investigate. Every factual row should have a source and date, while interpretation should be clearly identified as your own.
The board of directors, shareholder disclosures and financial statements supply different parts of a corporate governance brief. Keep their purposes distinct when building the record.
Start with a five-column table: claim, entity, date, supporting record and unresolved question. For the title row, use the official profile and appointment information. For a financial-performance row, identify the statement boundary and reporting period. For an impact row, state the metric and evidence needed.
Then write a two-paragraph explanation. The first should report what the documents establish. The second should explain what those facts mean for your chosen question and what remains uncertain. This structure prevents a gap in the record from being filled with an attractive but unsupported story.
Review the wording for hidden leaps. “Serves on the board” does not mean owns every business activity. “Announced a target” does not mean achieved it. “Reported growth” does not identify which person caused it. Replacing those leaps with precise verbs makes the brief both fairer and more informative.
For a final exercise, give another student the source table without your conclusion. Ask whether they can reconstruct the same factual account and which inference they would challenge. If the disagreement concerns evidence, revisit the record; if it concerns interpretation, state the reasoning more clearly.
The value of studying Anant Ambani through corporate documents is transferable business literacy. You learn to distinguish titles, entities, periods and outcomes, and to separate a primary statement from independent verification. Those habits remain useful long after a public figure stops trending, because they help you evaluate any prominent company's claims on a clear evidential basis.
Keep the original files or stable document references beside your notes. When a title changes or a new reporting period becomes available, update the relevant row while retaining the earlier dated record for historical comparison.
Sources
Source 1 · Source 2 · Source 3 · Source 4 · Source 5 · Source 6
Image credits: Cover: Bohoindian, source, CC BY 4.0. Resized and converted to WebP. Article image: Jpullokaran, source, CC BY-SA 3.0. Resized and converted to WebP.
Found an error or an outdated detail? Report a correction with the article URL and original source.