
PSO and Attock Refinery: Reading the Supply Deal
Understand reports of the PSO and Attock Refinery agreement renewal, what a supply contract covers, and which details require company disclosure.
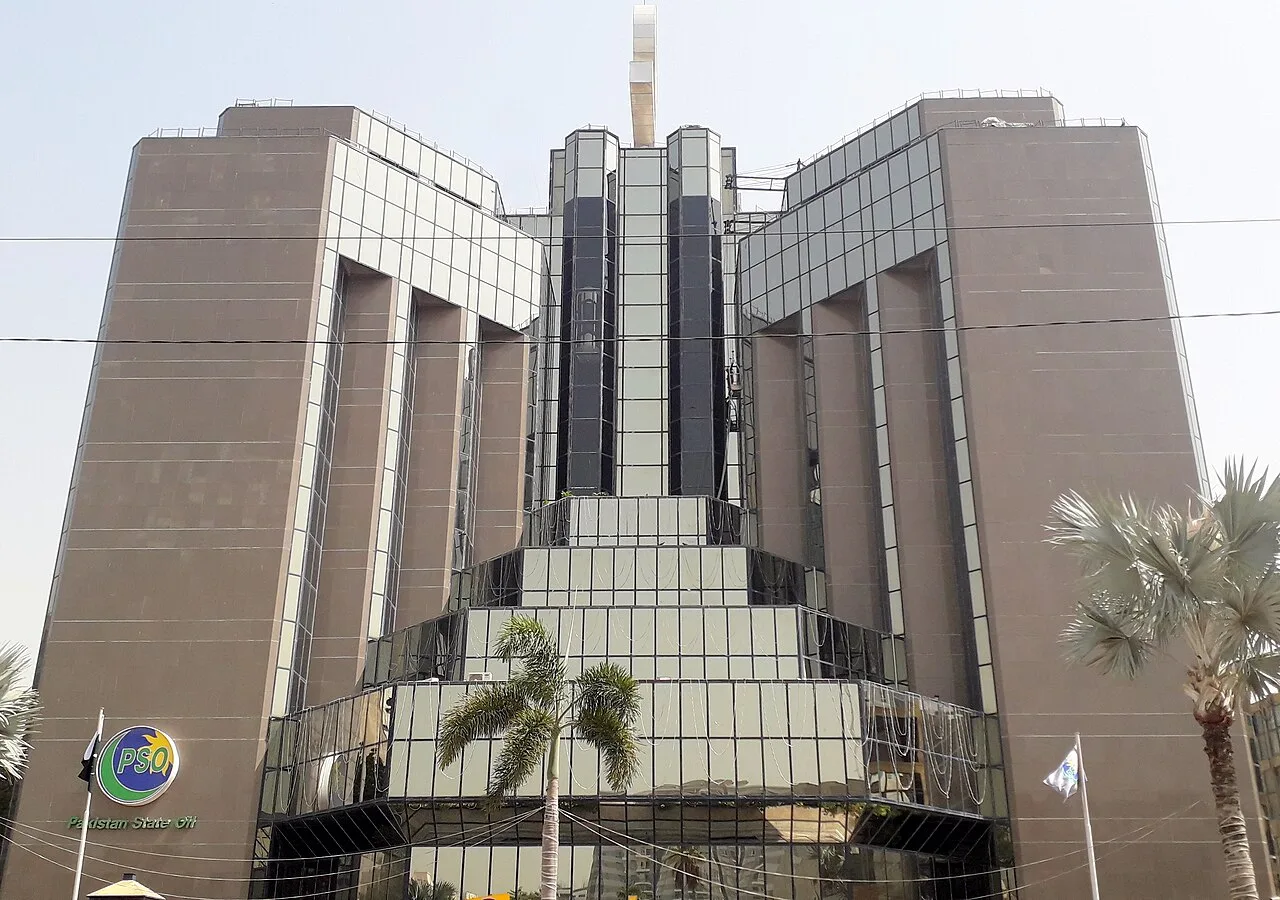
The reported PSO and Attock Refinery agreement renewal concerns a commercial supply relationship, not an automatic reduction in petrol prices or a guaranteed benefit for shareholders. The useful questions are what was approved, which organisations are involved, how delivery is measured and what evidence would establish implementation.
A report dated 29 October 2026 describes PSO board approval for renewal of a sale-purchase agreement with Attock Refinery. It reports an effective period from 1 July 2025 to 30 June 2030. Those particulars are attributed to the report; the signed agreement was not verified for this explainer. The discussion below separates that reported development from general lessons about petroleum procurement and contract reading.
Who are PSO and Attock Refinery in this transaction?
PSO and Attock Refinery are distinct legal entities with different operational roles. PSO's exchange profile describes procurement, storage and marketing activities, while Attock Refinery's reporting concerns its refining business. Understanding that distinction prevents a supply agreement from being mistaken for a merger or a change in ownership.
Use the full legal entity name when matching a disclosure. Attock Refinery is not interchangeable with every business using the Attock name. The exchange symbol ATRL identifies the listed refinery, while PSO identifies Pakistan State Oil. Similar branding does not make separate company records interchangeable.
A refinery processes feedstock into petroleum products. An oil marketing business arranges sourcing and distribution within its operations. Their commercial relationship can link production with customers, but each remains responsible for its own assets, costs and contractual obligations.
When studying the announcement, draw two boxes for the organisations and an arrow for the reported supply relationship. Add ownership only if a separate corporate document establishes it. This simple diagram prevents a common error: assuming every important agreement changes who owns the supplier.
The exact document matters as much as the names. An annual report can explain business activity, while a transaction announcement may describe a specific approval. Neither should be treated as a substitute for undisclosed contractual wording.
Does board approval mean the agreement has already been signed?
Board approval, authorisation to sign and completion of signing are different stages. The wording of the announcement determines which stage is established. An approval can permit executives to complete a transaction, but readers should not silently rewrite it as proof that every final signature and condition has been completed.
A renewal extends or replaces an existing arrangement under its stated terms. An addendum changes or supplements a document. These labels describe different relationships to earlier paperwork, so keep the terminology used in the verified source rather than treating every change as a brand-new contract.
The effective period can differ from the signing date or publication date. A report published later can describe an arrangement covering an earlier start. That timing difference calls for reading the documents carefully; it does not by itself prove misconduct or invalidate the arrangement.
Create a chronology with separate entries for approval, reported effective start, signing and operational delivery. Leave a field blank if no reliable record establishes it. A visible gap is more informative than an invented date added to make the sequence appear complete.
Ask what changed
A useful renewal analysis compares the previous and revised arrangements where both are available. Without that comparison, do not assume every clause is new. A headline about tighter controls may describe a specific amendment rather than an entirely different commercial relationship.
What does a supply commitment establish?
A supply commitment describes an obligation or arrangement within a contract's defined scope. Its meaning depends on product, quantity, timing and conditions. It is not automatically the same as physical delivery, refinery capacity or a guaranteed amount of retail sales.
A delivery schedule may organise supply into periods and locations. A total annual quantity can conceal uneven monthly requirements, while a monthly range may involve scheduling decisions. The precise interpretation requires the contract, not just an average calculated from a news summary.
Capacity and throughput are different. Capacity describes a capability under a specified basis, while throughput records processing over a period. A supply allocation does not prove the plant operates continuously at its capacity or that all output goes to one customer.
Use a clearly hypothetical example to understand the distinction. An agreement referring to 12,000 tonnes over a period does not prove that 1,000 tonnes arrive on the first day of each month. Transport, nominations and other contractual conditions may shape the schedule.
Do not attach this example's quantity to PSO or ARL. Its purpose is to show why a volume headline needs operational detail. The verified agreement text would be needed to establish the actual commitments, tolerances and exceptions.
Why do temperature and quantity measurement matter?
Liquid quantity measurements need a defined basis because volume, mass and temperature are related but distinct. A commercial handover must establish what was measured and under which conditions. General metrology guidance addresses measuring systems and conversion arrangements, but it does not tell us which exact provisions appear in this particular contract.
Volume describes occupied space, while mass describes the amount of matter measured by a mass unit. Density links the two under stated conditions. A litre and a tonne cannot be treated as interchangeable labels without a suitable conversion basis.
Temperature can change a liquid's volume. Two readings taken under different conditions may therefore require a common reference before they can be compared fairly. This is why a commercial document may specify measurement conditions rather than rely on an unexplained number of litres.
Custody transfer is the handover point at which measured quantity and related records become commercially significant. A meter reading, tank measurement and transport document may be compared through reconciliation. The governing method must come from the relevant agreement and applicable framework.
Calibration concerns the relationship between an instrument's indications and reference values. It is different from assuming that any digital display is inherently exact. A sound measurement record identifies the method, instrument and conditions, allowing discrepancies to be investigated.
| Contract-reading issue | What to establish | What to avoid assuming |
|---|---|---|
| Quantity | Unit, basis and timing | All figures are directly comparable |
| Quality | Specification and test method | A general label proves compliance |
| Delivery | Place, schedule and handover | Approval equals completed supply |
| Payment | Invoice and settlement basis | Sales immediately become cash |
| Measurement | Instruments and reference conditions | Every discrepancy proves fraud |
How do product quality and sampling provisions help?
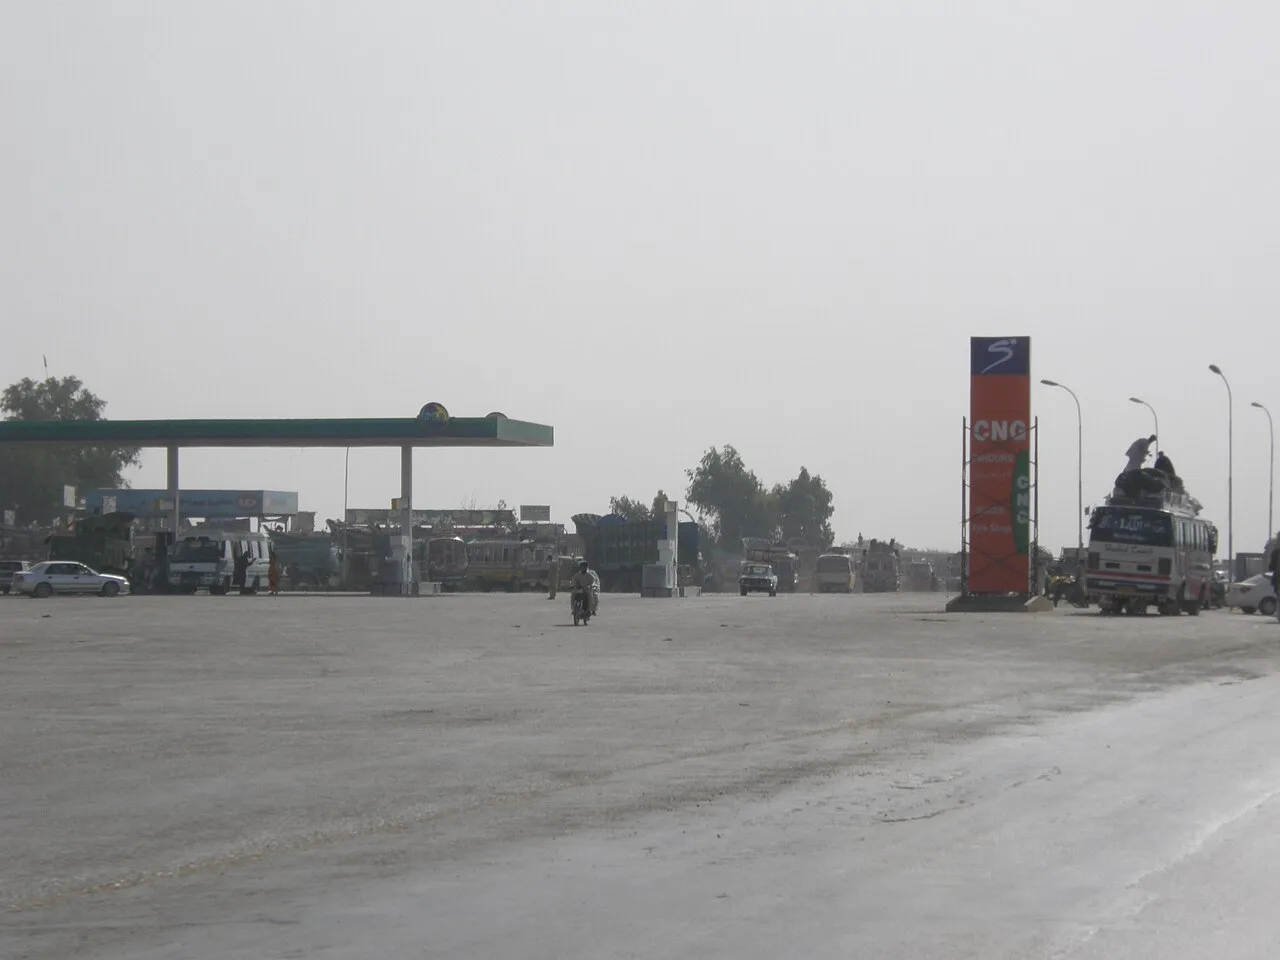
A Hyderabad station photographed in 2008 illustrates the downstream retail role, separate from refinery production and contractual supply commitments.
Product quality provisions define what the buyer is expected to receive and how compliance is assessed. Sampling and laboratory procedures can create evidence about a delivery, but the reliability of that evidence depends on method, identification and handling. A short summary rarely contains enough detail to reconstruct those procedures.
A specification should identify the relevant product characteristics. Petrol and diesel require different definitions, so a vague phrase such as “good fuel” is inadequate for technical acceptance. The actual limits and methods must be checked in the appropriate document.
A sample is useful only if it can be connected to the delivery it represents. Records should allow the parties to identify where and when it was taken and what happened before analysis. This is a general evidence principle, not a claim about an undisclosed clause in the reported renewal.
Inspection can help identify discrepancies before acceptance, while a documented disagreement process can organise later investigation. Neither eliminates every risk. The practical question is whether the procedure produces clear, reproducible evidence rather than merely more paperwork.
Avoid copying numerical temperature limits, settling periods or tolerance percentages from informal summaries into a supposedly definitive guide. Unless the primary document is available and verified, those figures should remain unconfirmed. Explaining why the clause matters is useful without pretending to know its final wording.
How should readers assess financial significance?
Financial significance depends on delivered volumes, margins, costs, payment timing and execution. A renewed relationship may support planning, but the contract headline alone does not establish additional profit. Start by identifying the economic mechanism, then look for evidence in the relevant disclosure and financial statements.
Revenue records sales under the applicable accounting framework; profit reflects income after relevant expenses. Cash flow records cash movements. These measures are connected, but they are not identical. An increase in sales can occur alongside pressure on cash if customers pay later.
Payment terms and a credit period affect working capital. Inventory can tie up funds before sale, while receivables represent amounts still to be collected. A business with substantial sales may therefore need financing to support operations. The effect depends on actual terms and collection experience.
Use a hypothetical comparison: a sale of 100 accounting units with costs of 96 leaves four before other items. Raising volume does not reveal the final gain unless the margin and additional costs are known. The same logic applies to claims that a bigger supply commitment must produce a proportional earnings increase.
Read financial periods consistently. A quarter, year and contract term are different windows. Comparing one quarter's result with a five-year commitment without explanation creates an impressive-looking but meaningless contrast.
Separate mechanism from forecast
“More reliable supply could help scheduling” describes a possible mechanism. “Profit will increase by a specific amount” is a forecast requiring assumptions and evidence. Keep those two levels of claim separate throughout the analysis.
Does a refinery supply agreement change retail prices or share prices?
A supply agreement can affect business operations, but it does not by itself set the notified retail price or determine the share price. Consumer pricing and market valuation involve additional variables. A responsible reading explains the possible connection without presenting an automatic or guaranteed outcome.
For the consumer, fuel pricing can involve product costs, currency movements and policy components under the applicable framework. A procurement arrangement is only one part of that chain. Lower uncertainty in sourcing does not necessarily mean a specified reduction per litre.
For a shareholder, the effect depends on what the market expected, what the agreement changes and how the business performs. A positive operational development can coexist with other costs or risks. The direction of a share price cannot be deduced from the word renewal alone.
Do not confuse a commercial margin in a price buildup with the company's final profit margin. The business still faces operating expenses, financing and other relevant items. Similar terminology can conceal different denominators and accounting meanings.
If analysing investment implications for coursework, build scenarios rather than predictions. State what would have to happen for revenue, profit or cash flow to improve. Then list the evidence that would test each assumption. This develops financial literacy without pretending to provide a trading signal.
What is a practical checklist for reading the PSO–ARL story?
Read the exact entities, document type, dates, quantities and qualification language before drawing a conclusion. Separate what a primary disclosure establishes from what a report attributes to other material. Then state the operational question the agreement might address and which parts remain unverified.
Begin with a one-page fact sheet. Record the organisations and source date, then separate reported approval from confirmed signing. Add the effective period in its own field. This prevents different dates from being combined into a false chronology.
Next, create a clause map with headings for product, delivery, measurement, quality and payment. Fill only what the available evidence supports. If a news report discusses measurement but not payment, the correct entry is “not established from this source,” not “no payment provisions.”
Check the exchange disclosures for the exact companies and reporting period. Official profiles are useful for identity, but an announcement list may not reproduce a signed contract. Absence from one visible page is not proof that no additional disclosure exists elsewhere.
A classroom case study
Give one group a short announcement and another a simplified hypothetical delivery record. Ask the first group what was approved and the second what was actually delivered. Bring the findings together and identify which questions neither document can answer. The exercise shows why commercial analysis needs more than one kind of evidence.
Finally, write a concise conclusion with three parts: the reported development, its plausible operational purpose and the limits of the available evidence. Keep general contract lessons separate from actual terms. A clear explainer should help readers ask better questions, rather than encourage them to mistake a headline for the full agreement.
Preserve the source notes with the worksheet. If a signed document or later company clarification becomes available, it can resolve specific gaps without requiring the entire analysis to be rewritten. That is the practical benefit of building the explanation around categories and evidence rather than unsupported predictions.
For a final reconciliation exercise, compare a hypothetical delivery record, invoice and payment receipt. Identify which document establishes quantity, which requests settlement and which shows cash movement. Add a separate production sheet if you want to calculate utilisation, because a sales record alone does not establish processing capacity used. In a real company study, preserve the PSX document date and issuer identity alongside each entry. These small distinctions help prevent a reader from turning an accounting record into a broader operational claim that it was never designed to support.
The petroleum supply-chain guide explains the physical route behind a commercial transaction. The petrol-price notice guide helps distinguish that transaction from a consumer price decision, and the economy-indicators guide provides wider statistical context. Use these distinctions when a headline jumps from an agreement to claims about households or the whole economy.
Sources
Source 1, Source 2, Source 3, Source 4, Source 5
Image credits: Cover: King Eliot, source, CC BY-SA 4.0. Resized and converted to WebP. Article image: Farhan from Karachi, Pakistan, source, CC BY 2.0. Resized and converted to WebP.
Found an error or an outdated detail? Report a correction with the article URL and original source.